AI Open Bar: why the bill always comes due
There is a precise moment when every great technological revolution stops being democratic and starts being profitable. With generative AI, that moment may be closer than our budgets assume.
Sandro Parisi, CEO Eudata
6/24/2026
There is a precise moment when every great technological revolution stops being democratic and starts being profitable. With generative artificial intelligence, that moment may be closer than our budgets assume.
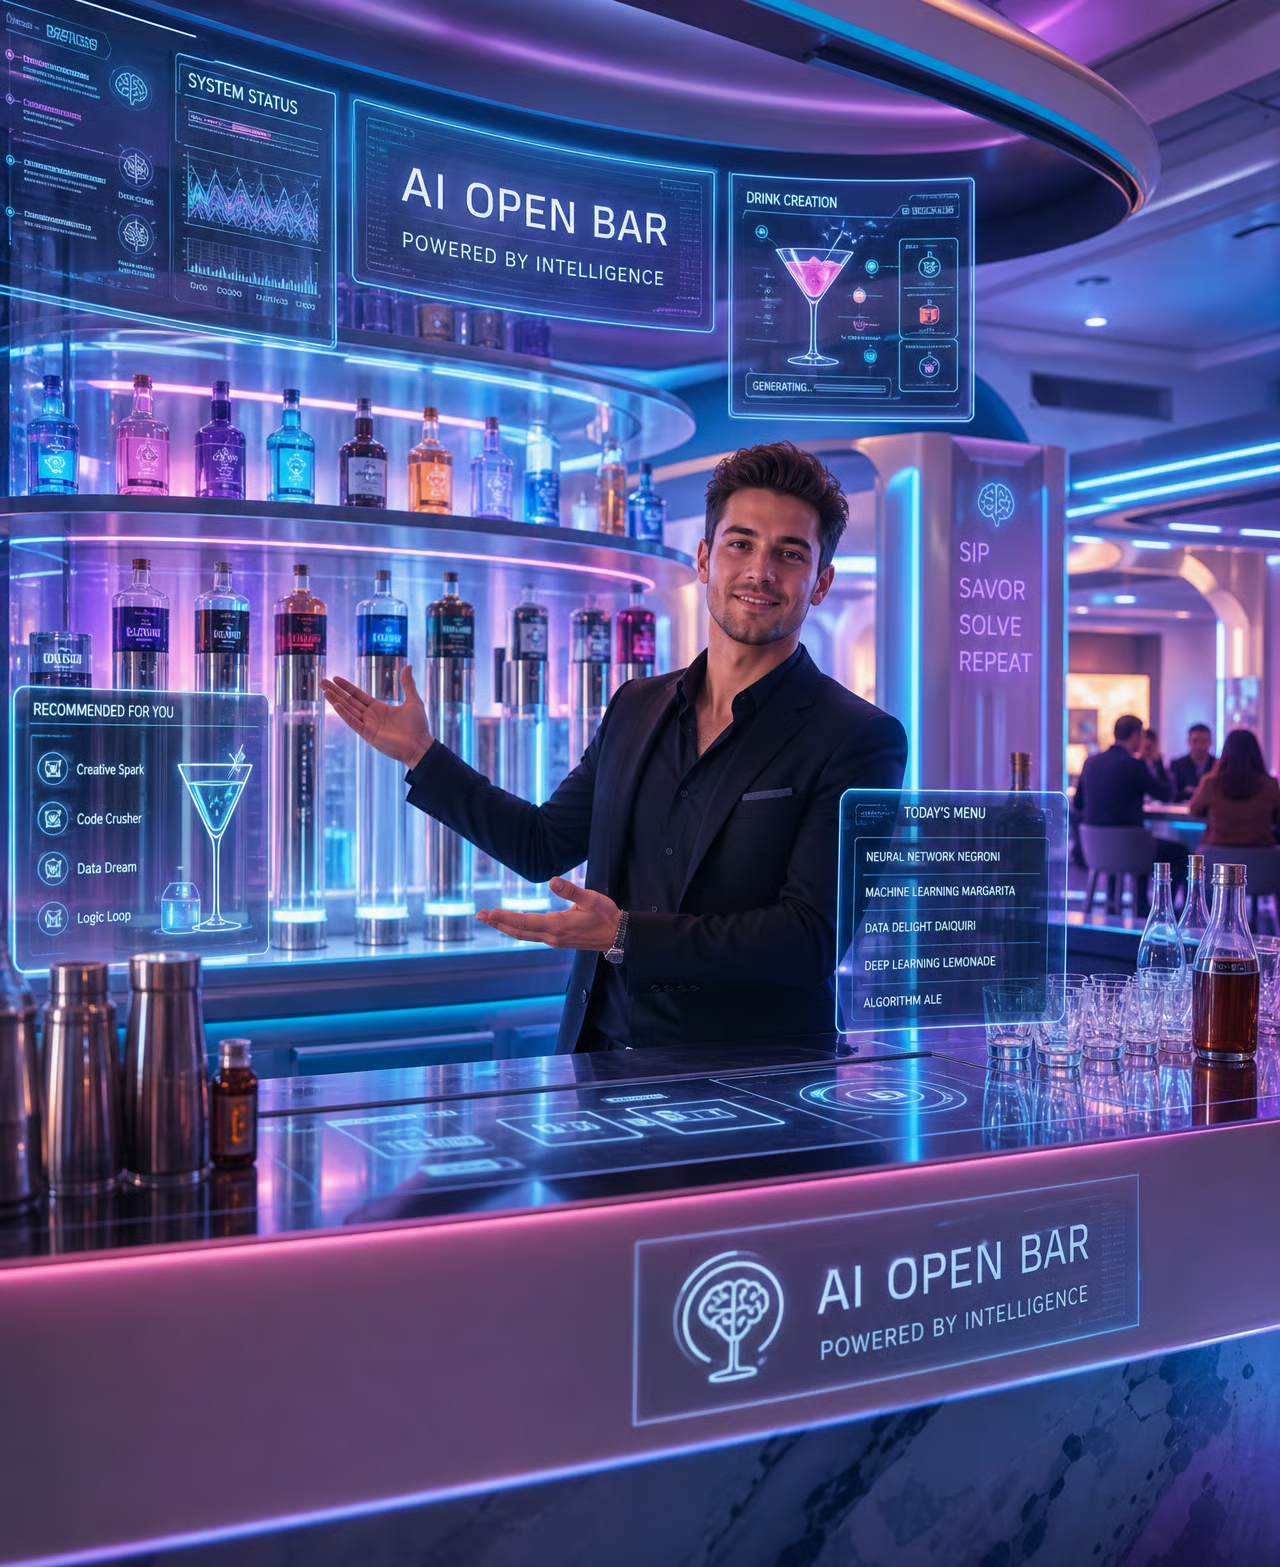
Let's use an after-work happy hour analogy: for the past three years, AI has in many ways been an open bar. Tokens at trivial prices, ever more powerful models, access with no barriers. The market's implicit message was simple: try everything, adopt it everywhere, the cost is almost zero and will keep falling. And companies responded exactly as expected: with enthusiasm and speed, but too often without a strategy or any deep reflection on what they were choosing (or not choosing).
The problem with open bars, though, is that somebody pays the tab. And it is usually not the one who poured the drinks.
Launch, Scale, Monetize: the script we know
If you have worked in the digital ecosystem over the past twenty years, you will recognize this sequence. It is the logic by which market dependence is built in three acts.
Launch: you enter with an excellent, accessible product, often below cost. The goal is not immediate margin, it is penetration. OpenAI today loses about 1.35 dollars for every dollar it earns. But that is not a mistake, it is a strategic choice.
Scale: the product becomes infrastructure. Companies integrate, build workflows, adopt the ecosystem. Teams get used to it, processes come to depend on it, and in this case people are even laid off. Stopping at that point is a problem, because it not only costs more than carrying on, but to stop I have to rebuild entire supply chains that were dismantled.
Monetize: once the dependence is structural, prices can normalize. Not necessarily with an announcement, not necessarily abruptly, but with the mathematical certainty of whoever controls infrastructure that is critical to your processes. And here, if you got it wrong at the start, going back is very, very complicated.
Average monthly corporate spending on AI grew by 36% between 2024 and 2025, even though the cost per million tokens fell by 50%. Goldman Sachs estimates a 24-fold increase in agentic consumption by 2030. Prices go down, but dependence, and therefore exposure, goes up.
The lock-in nobody names
When people talk about technology lock-in, they immediately think of the classic single-vendor trap: you use one tool, you are tied to that tool. But AI lock-in is more sophisticated and more dangerous.
It is not the tool that locks you in. It is the ecosystem. Microsoft Copilot works magnificently, but it works magnificently inside Microsoft 365, Teams, Azure and Dynamics. Every increase in value you get from AI reinforces the logic of staying in the vendor's ecosystem. Not because you are forced to. Because leaving means rebuilding, integrating, or giving up that super efficiency, which however comes at a high price and ties you to processes that are not always aligned with the company's needs and prerogatives.
The same goes for cloud infrastructure, reasoning models and agentic platforms: every architecture designed by the vendor to maximize value inside its own stack is by definition an architecture that maximizes your dependence on that vendor.
Add the agentic multiplier (every complex task structurally consumes 3 to 9 times the tokens of a direct call, with real costs that can match 2023 GPT-4 Turbo levels) and you have the full picture. An opaque cost, growing with adoption, on a platform you do not control.
Three detonators no CFO has in their model
The costs you know about (tokens, licenses, compute) are only the visible part. There are three structural factors that the market tends not to price in, and that could radically change the TCO of AI in the coming years.
The physics of AI. Artificial intelligence is not immaterial software. It is data centers, energy, hardware. A hyperscale data center consumes gigawatts. The most advanced chips (3-2nm) are produced almost exclusively by TSMC in Taiwan, a single point of geopolitical vulnerability for the entire global supply chain. Rare earths, helium, water: physical, scarce, geopolitically sensitive resources.
The financial instability of providers. The big AI companies are burning capital at an unsustainable rate. When debt becomes more expensive and investors ask for returns, token prices, artificially compressed today, will normalize toward profitability. The dependencies you will have built in the meantime will remain.
The legal factor. The American CLOUD Act and the PATRIOT Act require any US tech company to hand data over to the US government on request, even if the servers are in Europe, even if the contract says otherwise, even if the GDPR says otherwise. For those operating in regulated sectors (finance, healthcare, defense, energy) this is not a theoretical risk. It is a legal certainty.
The answer is not technological nationalism
It would be wrong to conclude that the solution is to avoid the big international players. GPT-5, Claude, Gemini: these are powerful models with real capabilities, which European companies must be able to use in order to stay competitive. The question is not which models, but who governs them and when to use them.
Arthur Mensch of Mistral AI has said that we have about two years to build a credible European supply chain. Not to shut ourselves off, but to have an alternative. The difference between dependence and strategic choice is built before the dependence becomes structural, not after.
The real defense of the European market lies in an integrable supply chain: architectures that let you use the best models available today, without handing any vendor control of your processes, data and business decisions.
ConvyAI: the harness that puts the customer at the center
Eudata has been working on exactly this problem for years, even before it became urgent.
ConvyAI is an agentic orchestration layer that sits between your processes and the AI models on the market. It does not compete with the models: it uses, governs and measures them for you. It does not ask you to choose a single AI vendor: it lets you choose the best model for each task, change it when conditions change, and measure its real cost and effectiveness.
In concrete terms, this means:
Model independence. ConvyAI is LLM-agnostic by design. GPT, Claude, Gemini, Mistral, open source models: you can orchestrate them all, choose the most suitable one for each process, and migrate without rebuilding the architecture. Vendor lock-in on the AI model is structurally impossible.
Intelligent token routing. Not every task requires the most powerful (and most expensive) model. ConvyAI routes each request to the optimal model for cost and quality, with a documented reduction in real AI costs of between 40% and 70%.
Continuous governance and auditability. Every agent decision is traceable, every workflow is auditable, every anomaly is detectable. Human-in-the-loop is not an option: it is an architecture. Because autonomy without governance is not efficiency, it is unpriced risk.
Omnichannel and enterprise integration. ConvyAI orchestrates channels, processes and models and uses back ends without upending them: CRM, ERP, legacy systems. It is an orchestration infrastructure that integrates with what you already have, without requiring you to rebuild your stack.
Data sovereignty. Your data stays under your jurisdiction, with full visibility on where it is processed and by whom, and the ability to choose what to do with it. It is not just GDPR compliance: it is an architectural choice that protects your know-how and your competitive position.
The six questions every CXO should ask right now
Before signing your next AI contract, before extending adoption to new processes, ask yourself:
- Where is my data, and under which jurisdiction?
- Who controls the infrastructure of the model I use?
- What happens to my processes if geopolitical conditions change?
- How much know-how am I transferring outside my organization?
- Is my TCO calculated on price-normalization scenarios, not on today's prices?
- Can I change vendor tomorrow without rebuilding everything?
If you do not have certain answers to all six, you are building a dependence, not a strategy.
The tab is coming. The question is whether you are ready to pay it.
The AI open bar has been an extraordinary accelerator of adoption. It lowered the barriers, proved the value, convinced the boards. But the open bar was paying for a precise logic: create the market, then govern it.
The companies that come out ahead from this phase are not the ones that adopted the most, they are the ones that adopted with coherent architectures. The ones that can say: I use the best models in the world, but I control them. My processes are efficient, but they are mine. My data generates value, and stays under my governance.
Eudata and ConvyAI exist to make exactly this possible: an AI adoption that is not a bet on a vendor's future behavior, but a strategic choice that puts the company (its customers, its data, its processes) at the center.
The open bar will end. Those who have built a governance architecture are already ready for what comes next, and to win in the market thanks to AI.
Do you want to explore how ConvyAI can protect your AI strategy and reduce your exposure to platform lock-in? Contact us or explore our enterprise use cases
Stay connected!
© 2025. All rights reserved.
Eudata s.r.l. SB
Via dei Valtorta 48, 20127, Milan
P.IVA 12421000154
info@pec.eudata.biz
Subscribe to our newsletter to stay updated on the AI landscape